
What Is Loss Assessment Coverage?
 By
Key Takeaways
- Loss assessment coverage kicks in when your HOA or condo master policy doesn’t cover the full cost of a shared-area claim, leaving you and your neighbors to split the difference.
- Coverage typically costs just a few extra dollars a month and can usually be purchased in amounts from $10,000–100,000.
- Most condo policies include $1,000 of loss assessment protection automatically.
- It only covers one-time assessments tied to a specific loss, like storm damage or an injury in a common area.
- If you live in a condo, townhome or HOA neighborhood, this coverage is a cheap way to protect your emergency fund from a surprise bill.
Flaming elevators! Roofs torn off by tornadoes! Lobby floors so slick they could double as an ice rink! (That last one sounds kind of fun, but it can do a lot of damage to an elbow or a tailbone.) What do all these risks have in common?
They’re all risks that come with living in a community with shared amenities—and they’re all insured by loss assessment coverage.
Quick Answer
Loss assessment coverage is an optional endorsement on your condo or homeowners policy that pays your portion of a shared-area loss when your HOA’s master policy comes up short. Think storm damage to a roof or an injury in a common area. It costs just a few dollars a month, and if you live with an HOA, it’s a must-have.Here’s what that means for your wallet, what the coverage actually pays for, and how much you should carry.
What Is Loss Assessment Coverage?
Loss assessment coverage (also known as special assessment insurance) is an optional layer of property insurance. You can add it to your condo, townhouse or homeowners policy to pay your share of a loss in a common area. (And FYI, even though apartment complexes and mobile home parks have common areas, loss assessment coverage doesn’t come into play if you live in one of those.)

If you’re living that shared community life, you’re probably loving the swimming pools, playgrounds and golf courses. But that isn’t all you and your neighbors share! You also have to split the cost for those amenities—and that includes a portion of insurance claims if something goes wrong. That’s where having loss assessment coverage can come in real handy.
(By the way, loss assessment coverage can be especially important for condo owners because they typically share responsibility for more of the building and common areas than townhome owners do—but it’s still an option for you townhouse peeps.)
How Does Loss Assessment Coverage Work?
Your HOA carries a master policy for your neighborhood or condo common areas, which will kick in if an incident happens (think storm, fire, lawsuit, etc.). But like any kind of insurance, there are limits. Massive accidents like tornadoes, fires and slippery floors can destroy roofs, elevators and lower backs—and losses like those can get expensive! Sometimes, your HOA’s master policy limit (how much it will pay out for a covered event) won’t cover the full cost of the incident.
When a loss reaches a certain cost level (or if it isn’t covered by the master policy), your HOA will be liable for whatever’s left to pay. Guess where the payment comes from? Your condo or HOA will assess the loss to you and your fellow homeowners. (That’s where the term loss assessment comes from.)
Now even without separate loss assessment coverage, most individual policies for a condo will cover you for $1,000 when there’s an incident. (That $1,000 goes toward either your share of a shortfall above the master policy's limit or your share of its deductible.) So if you live in a condo, at least you’ve got that going for you. But if you have loss assessment coverage, it kicks in (no matter what kind of home you own) above that initial grand and might just keep you from having to drain your emergency fund to cover your community obligation.
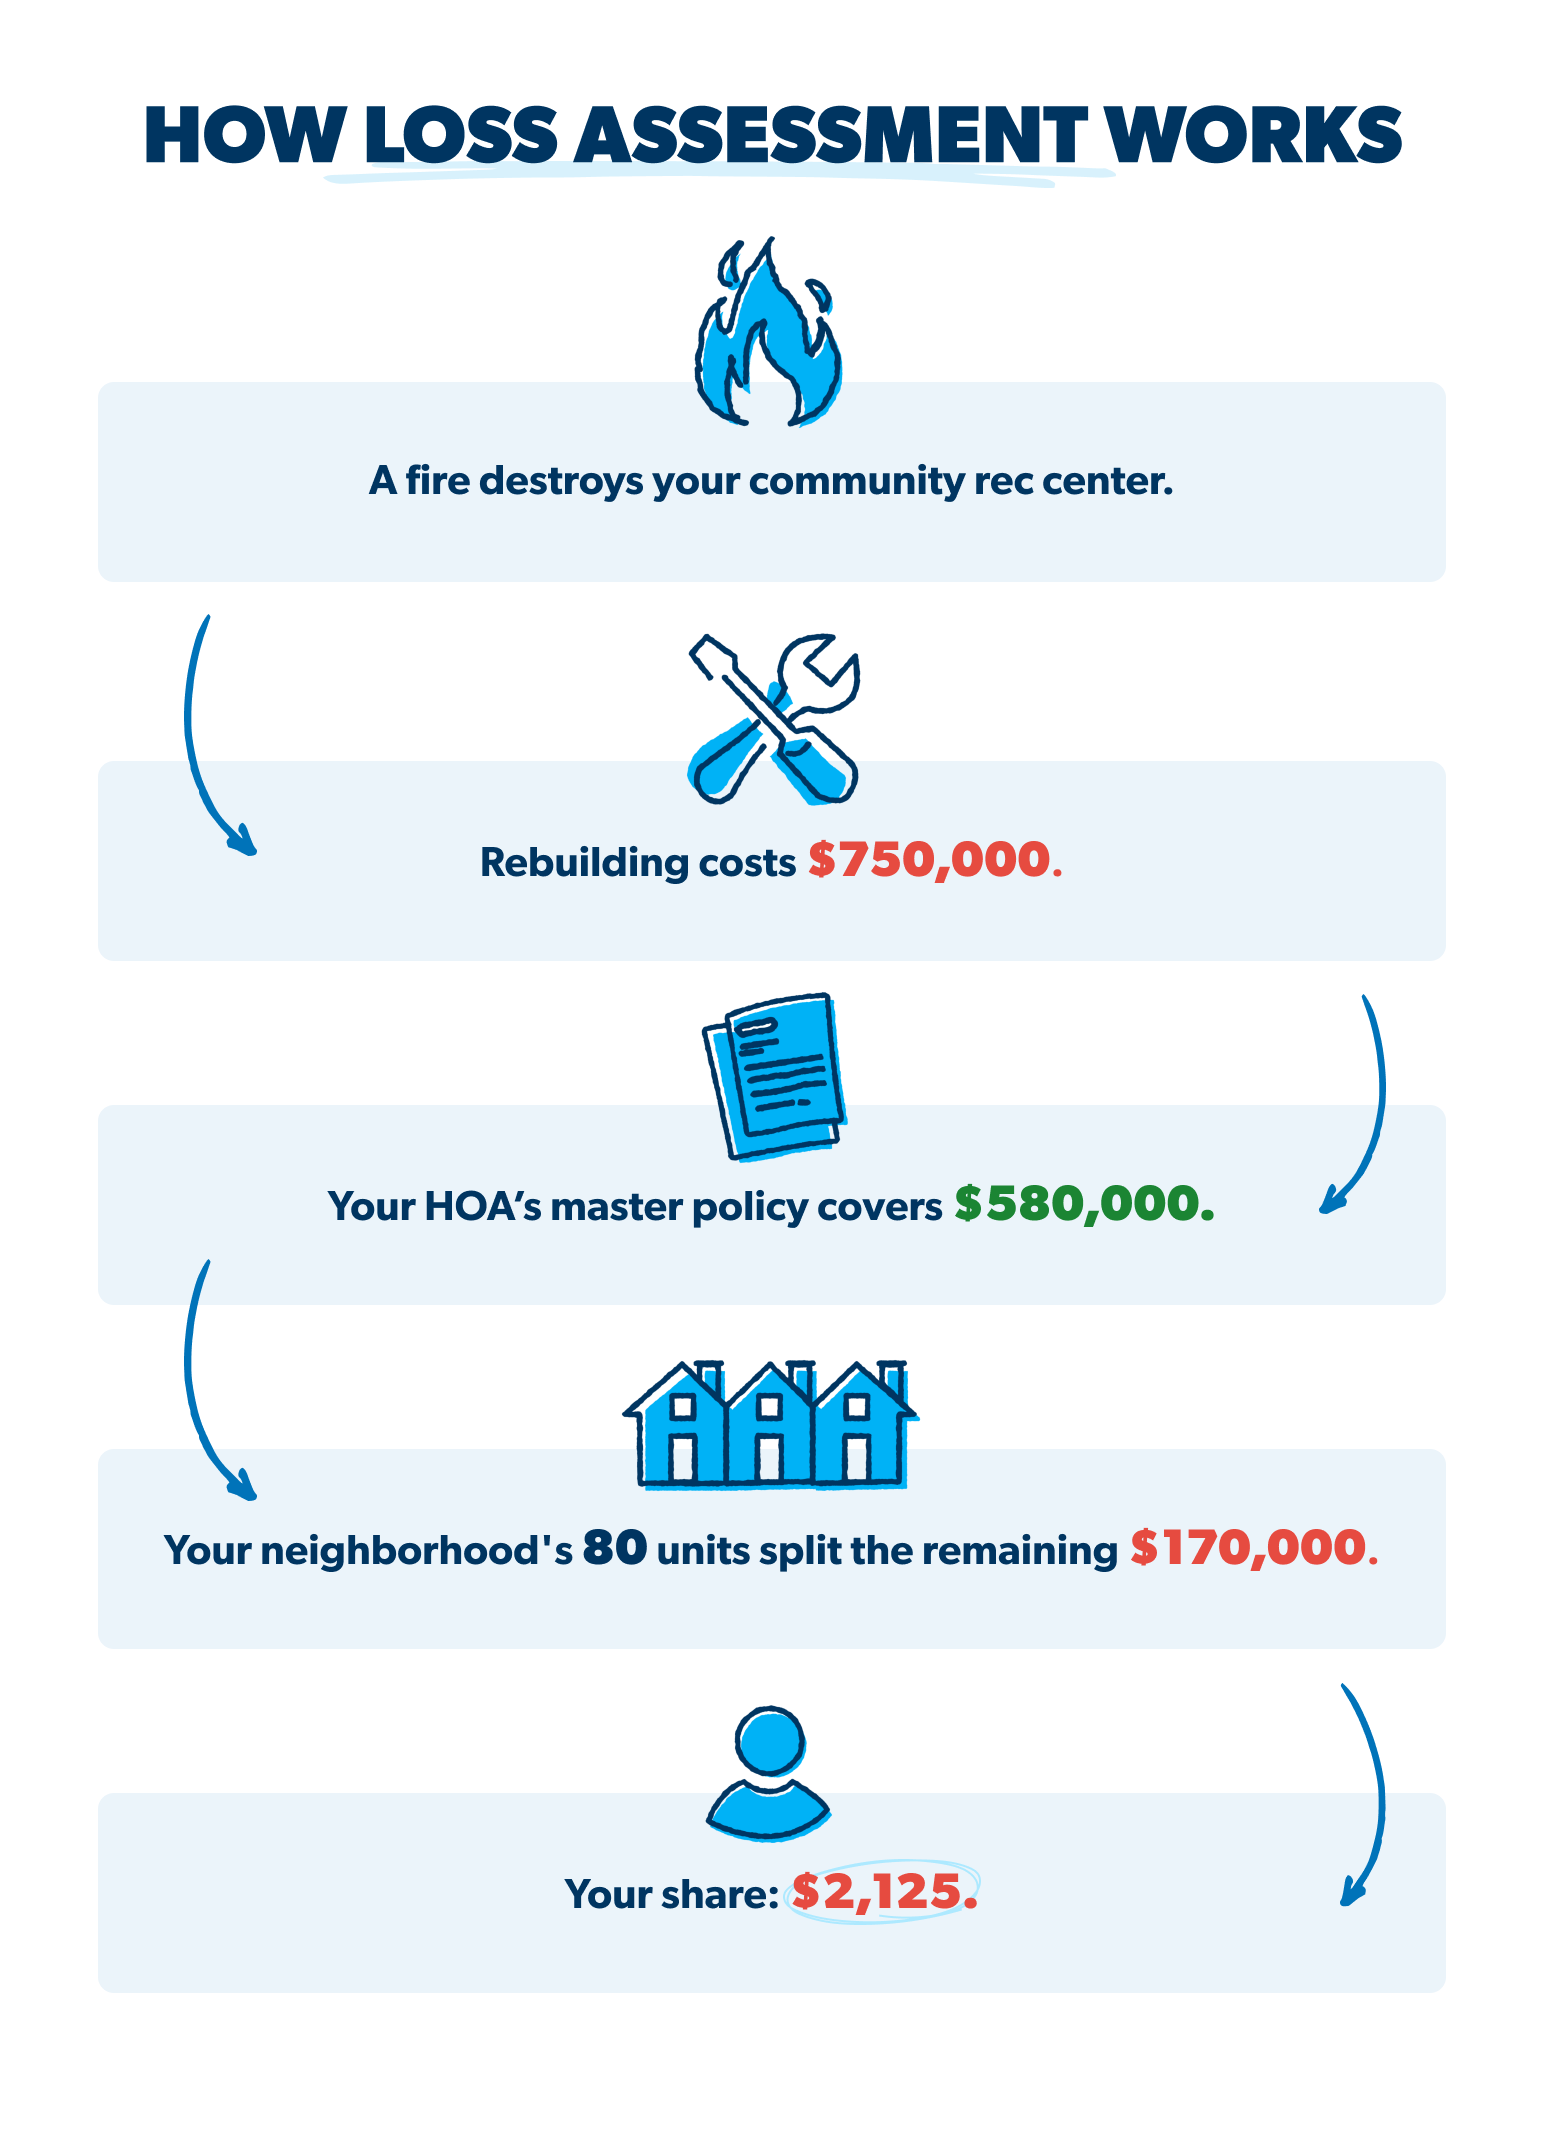
Here’s an example of how loss assessment coverage works: Lightning strikes your community rec building, starting a fire that burns it to the ground. The rebuild costs $750,000, but your HOA’s master policy tops out at $580,000, leaving a $170,000 gap. With 80 units in the complex, the HOA sends every owner a $2,125 assessment bill.
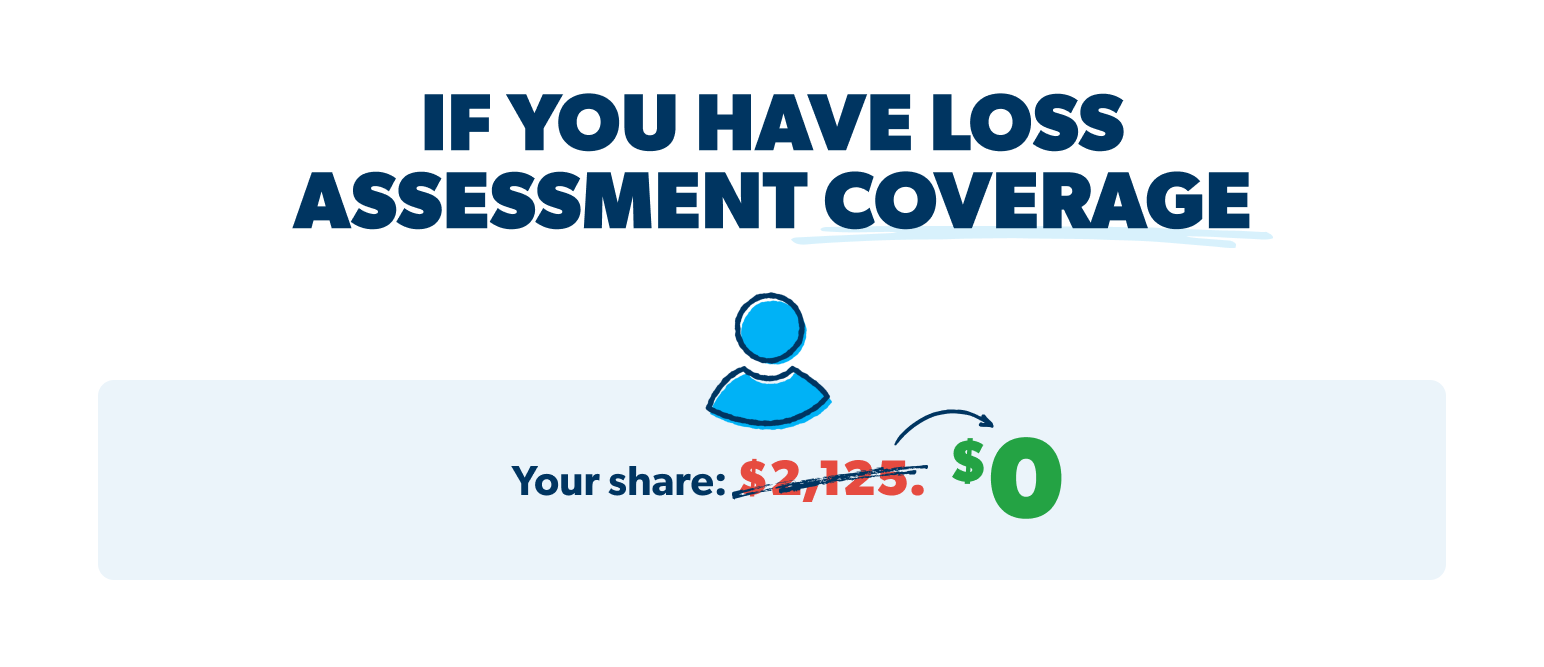
If you’ve got loss assessment coverage, that $2,125 gets paid by your insurance company instead of your emergency fund. That means you get to keep moving toward your goals instead of circling back to build up your savings again.
What Does Loss Assessment Cover?
If you do own a property in a shared community, there are three basic kinds of loss that loss assessment can help cover:
- Property damage
- Medical expenses
- Liability costs
Loss assessment liability coverage works alongside your separate personal liability insurance. Think of loss assessment as covering your share of the HOA’s bill, and personal liability insurance as covering claims made directly against you.
And did we mention that loss assessment coverage only applies to townhomes, HOAs and condos? (Yeah, we did, but it’s important to note so nobody spends money on a useless insurance policy.)
What Is Loss Assessment Coverage in a Condo Insurance Policy?
Ever see the movie Twister? If not that one, maybe the newer one, Twisters? (It's totally different.) Well, those movies make it easy to imagine the kind of damage a tornado could do—a storm like that could demolish your whole condo. If the repair costs add up to more than the master policy limit, your condo association might make each condo owner pitch in to cover the rest of the bill. If you have loss assessment coverage, it can help cover some or all of your portion of these expenses, so you don’t end up paying out of pocket.
Loss assessment coverage can also help if you’re the one at fault. Let’s say your mischievous 9-year-old is playing with matches and accidentally starts a fire—the whole idea probably gets you sweating just thinking about it! If that fire spreads to other units, your HOA might require you to pay its full deductible since the fire was technically your fault. In a situation like that, you’d have a lot to deal with, but at least loss assessment coverage could ease some of the financial pain.
What Are the Limits for Loss Assessment Coverage on Condo Policies?
While you’re asking about what loss assessment does cover for condos, it’s worth asking what’s outside the scope. Imagine your condo HOA decides to spruce up its landscaping. As nice as that sounds, you can’t use loss assessment to help you cover your share. That’s what gain assessment coverage is for—just kidding, that kind of policy doesn’t exist.
What Is Loss Assessment Coverage in a Homeowners Insurance Policy?
There are plenty of differences between house and condo living, but loss assessment coverage works about the same in both types of housing. For example, if your neighborhood includes a golf course, it’s easy to imagine a stray ball slicing the wrong way and smacking a nearby jogger upside the head. And what do you know? He winds up with a concussion and some hospital time. Then, the medical bills exceed your HOA’s master policy limits.
You can see where this is going. Every homeowner in the HOA will get a bill for their personal share of the remaining costs to help heal that poor noggin. But if you have loss assessment coverage, it will cover at least some (and often all) of your share.
What Are the Limits for Loss Assessment Coverage on Homeowners Policies?
Let’s say your HOA decides to improve the walking paths in your neighborhood and sends you a bill for your share of the cost. Can you make a claim on your loss assessment policy to cover it? No way! Like we said earlier, that policy only covers the cost of losses like damage and lawsuits, not new improvements in the neighborhood.
Interested in learning more about homeowners insurance?
Sign up to receive helpful guidance and tools.
Is Loss Assessment Coverage Different for Condo Owners vs. Homeowners?
While the mechanics are the same, loss assessment coverage is more common for condo owners than for those in traditional HOA neighborhoods. Loss assessment coverage for condo owners will naturally cover a few different areas (like elevators) that a loss assessment endorsement added to a homeowners insurance policy wouldn’t.
|
Condo |
Home in an HOA |
|
|
Common Areas Covered |
Lobbies, elevators, parking structures, tennis courts, shared roofs, etc. |
Neighborhood amenities like clubhouses, pools, playgrounds and private roads |
|
Assessment Triggers |
Building-wide damage (fire, storm, structural) that exceeds the condo association’s master policy |
Shared-amenity damage or injury that exceeds the HOA’s master policy |
|
Example Risk |
A lobby fire that costs more to repair than the building’s master policy limit |
An injury on the community playground that racks up bills past the HOA’s liability limit |
|
Coverage Availability |
Very common—often required by the condo association |
Optional, but worth adding if your HOA has shared amenities |
How Much Loss Assessment Coverage Do I Need?
Before you settle on a coverage amount, pull out your HOA’s bylaws and master policy—whether you’re in a townhome, condo or other HOA community—and check for:
- Your master policy’s coverage limit (how much protection your HOA already has before you’re on the hook)
- The master policy’s deductible (that cost sometimes gets passed down to residents too)
- Any stated special assessment rules (some bylaws spell out exactly how assessments get divided among owners)
- Any minimum loss assessment coverage your HOA requires or recommends you carry
Don’t just check your HOA’s coverage limit—check its deductible too. If that number is high, your community could get hit with a bigger bill than you’d expect. RamseyTrusted® insurance pro Michael Ell recommends, "Call your agent and ask: If my HOA bills me for its deductible, how much of that will my policy pay?"
"Call your agent and ask: If my HOA bills me for its deductible, how much of that will my policy pay?"
— Michael Ell, RamseyTrusted® insurance pro
Once you know the number, make sure you budget for the extra premium.
How Much Does Loss Assessment Coverage Cost?
Loss assessment coverage will typically run you just a few extra dollars a month on your townhome, homeowners or condo insurance policy. So if you’re willing to drink one less fancy latte a month, you can swing this.
Most base condo policies include $1,000 of loss assessment coverage automatically. Policies for single-family homes and townhomes sometimes do, but you should check your policy to make sure. If you want more protection than you have, you can typically purchase loss assessment coverage in amounts from $10,000–100,000.
Why Is Loss Assessment Coverage Important?
Loss assessment coverage is important because life is messy. Think about it—something as random as a gust of wind can blow the tiles off your condo roof, fan the flames of a lobby fire, or send a wayward golf ball straight into your neighbor’s face. Stuff happens. And when it does, loss assessment coverage can be a lifesaver! It’s affordable, and it could save you thousands if your community ever gets hit with a shared-area disaster. So get the coverage—your emergency fund will thank you.
Do I Need Loss Assessment Coverage?
If you live in a condo, townhome or HOA neighborhood, the answer is yes—get loss assessment coverage. If you don’t live in a shared community, you don’t need it, plain and simple. But if you do, this isn’t something to brush off. Check your community’s bylaws, your master policy limits, and your own deductible amounts, then add the coverage. It’s cheap, and it keeps a surprise assessment from turning into a hit on your emergency fund.
How Do You Get Loss Assessment Coverage?
Whether you’re just now moving into a shared community or you’re already in one, adding loss assessment coverage to your required homeowners or condo policy should be pretty easy. Your insurance agent can give you the details and pricing options. As we said earlier, it’s typically just a few extra dollars a month for a lot of coverage.
Sitting down with a RamseyTrusted insurance pro can take the mystery out of any kind of homeowners insurance—including loss assessment coverage. They’ll help you understand what’s covered—and what isn’t—while making sure you have everything you need to protect your home.
Plus, working with an independent agent who isn’t tied to one insurance company might help you save money on homeowners insurance. That’s because they can shop around for rates from dozens of different companies and find the best deal for you.
Next Steps
- Review your HOA’s master policy deductible, coverage limit and special assessment rules in the association bylaws.
- Confirm the loss assessment limit on your condo or homeowners policy and whether it covers the risks your community actually faces.
- Connect with a RamseyTrusted insurance pro to add or adjust loss assessment coverage before the next surprise assessment shows up in your mailbox.
-
What’s an example of loss assessment?
-
Here’s an example of loss assessment: A storm rips the tiles off your condo building roof. The cleanup and repair bill runs higher than your HOA’s master policy, so your HOA passes the extra expense on to you and your condo neighbors. Loss assessment insurance helps you pay for that surprise assessment.
-
Is loss assessment the same as a deductible?
-
Your loss assessment policy is not the same thing as the deductible in your shared community’s master insurance policy. Your HOA will have to pay its master policy’s deductible before the insurance company will pay out on a claim for loss or damage. Those deductibles are often assessed to individual homeowners in the community, who must foot the bill equally. But you can use your personal loss assessment policy to help cover your own share of the HOA deductible.
-
Does loss assessment coverage pay for HOA fee increases?
-
No. Loss assessment coverage only kicks in for a special assessment tied to a specific covered loss—think storm damage or an injury in a common area. It won’t cover routine maintenance costs or a general bump in your regular HOA fees.
-
Is there a deductible for loss assessment claims?
-
Usually not. Most policies apply your loss assessment coverage once the bill goes above the small amount—often $1,000—that’s already built into your base policy.
-
Does loss assessment cover earthquake or flood damage?
-
Only if your personal policy covers those perils in the first place. If your base condo or homeowners policy excludes floods, your loss assessment endorsement won’t step in to cover a flood-related assessment either.
Get Weekly Insights Delivered Straight to Your Inbox
Did you find this article helpful? Share it!

About the author
Ramsey Solutions

Get proven Ramsey answers fast.