
What Are Stocks and How Do They Work?
 By
Key Takeaways
- A stock is a share of ownership in a company (also called an equity). Buy one and you become a part owner.
- You make money on stocks two ways: the price goes up (appreciation) or the company pays you dividends.
- Stock prices rise and fall based on company performance, investor emotions and broader economic conditions, which makes investing in single stocks risky.
- We recommend growth stock mutual funds over single stocks because they spread your money across many companies.
- The smart investing path: Invest 15% of your income through your 401(k) and a Roth IRA for the long haul.
Stocks come up everywhere. On the news. In retirement conversations. At the family reunion where your cousin-in-law corners you with a hot stock tip that’s a “sure thing.” But if you’ve ever nodded along while secretly wondering what stocks actually are and whether you even need them, you’re not alone. Let’s break it down.
Quick Answer
A stock is a share of ownership in a company, also called an equity. When you buy stock, you become a part owner of that business and can benefit if the company grows more valuable over time. You make money two ways: the stock’s price rises or the company pays you dividends.Now, stocks can be risky. Buy them the wrong way and they’ll hurt you. But used the right way, they’re one of the most powerful wealth-building tools available. The difference is knowing what you’re doing. Not chasing a hot tip.
What Are Stocks?
A stock is a share of a company—or a tiny piece of ownership (also called an equity). Picture a sheet cake cut into a hundred small squares. If you buy one square, you own that slice. When a company wants to raise money to grow the business, it sells shares to the public. And when you buy stock, you become a part owner of the company with a real stake in what happens next.

Buying stocks is one of the most common investment strategies. Over time, the value of the stock can grow and produce a return on your initial investment through the power of compound growth. But that value is directly tied to how the company performs and how confident investors feel about it, which is why stocks can swing up and down.
Stocks always carry risk. If the company struggles, you could lose the money you invested. If you invest the right way (we’ll tell you how), that risk becomes very manageable. But if you invest recklessly and treat the stock market like your own personal casino, you could end up with a mess on your hands.
How Do Stock Prices Go Up and Down?
A stock’s price is driven by supply and demand. When more people want to buy a stock than sell it, the price rises. When more people want to sell it than buy, the price goes down. Those buying and selling decisions are usually influenced by three things: how the company is performing, how investors are feeling, and what’s happening in the overall economy. Here’s a closer look at each one:
- Company earnings and performance: A strong earnings report tells investors the business is healthy. That draws more buyers and pushes the price up. A disappointing quarter does the opposite.
- Investor emotions: Facts don’t always control price swings. Sometimes they move on how investors feel about the company’s future. Fear and excitement are powerful market forces.
- Broader economic conditions: Interest rate changes, inflation data and economic slowdowns can ripple across the entire market, not just one stock.
No one can reliably predict these swings, so trying to time the market is a losing game. Don’t waste your energy guessing what the market will do next. The investors who win are the ones who stay in the market for the long haul.
What Is the Stock Market?
The stock market is where brokers buy, sell and trade stocks. It’s a network of exchanges where stock prices are set in real time.
Stockbrokers are people who buy and sell stocks, usually on behalf of clients they represent or funds they manage. They’re watching stock market activity constantly and tracking real-time updates on how the stocks are performing.
When a private company decides to sell shares to the public for the first time, that’s called an initial public offering (IPO). It’s how a company “goes public” and lists its stock on an exchange.
Stock Exchanges: The NYSE and Nasdaq
The stock market isn’t necessarily a physical location, although the New York Stock Exchange (NYSE) is housed in an actual building on Wall Street. Nasdaq is an electronic exchange where brokers use computer networks instead of a trading floor to buy and sell.
Stock Market Indexes: The Dow and S&P 500
If you pay any attention to financial news, you’ll hear a lot about the Dow. It’s short for the Dow Jones Industrial Average, a list of 30 large public companies traded on the NYSE and Nasdaq. Think of it as a quick reference for how top companies are performing. Another index you’ll hear about a lot is the S&P 500. It tracks 500 leading U.S. companies and is the most widely followed measure of overall market performance.
What Are the Types of Stocks?
The two basic types of stocks are common and preferred. All stocks are shares of a company, but they get packaged and sold in different ways depending on how you want to invest.
Common Stock vs. Preferred Stock
Before we get into the different ways to invest in stocks, it helps to know the two basic types of stock a company can issue:
- Common stock is what most people mean when they say stocks. As a common stockholder, you own a slice of the company, may receive dividends, and typically get a vote on major decisions. But if the company goes bankrupt, common stockholders are last in line to be paid back.
- Preferred stock works differently. Preferred shareholders generally don’t get voting rights, but they get a bigger piece of dividends and assets than common stockholders. Dividends on preferred stock are usually fixed and paid out before any common stockholders see a cent. Think of it as a hybrid between a stock and a bond.
Beyond the types of stocks, there’s also the question of how you buy them. That’s where single stocks, ETFs and mutual funds come in.
Single Stocks
Buying single stocks gives you ownership in a specific company. Because that puts all your eggs in one basket, single stocks can be extremely risky. It’s smarter and a lot less stressful to diversify your money and not have it all invested in one company.
Exchange-Traded Funds
Exchange-traded funds (ETFs) are similar to mutual funds. Each one is filled with stocks from many different companies, but ETFs are bought and sold like single stocks.
Most ETFs work like index funds too. They’re filled with stocks from high-performing companies known for being reliable investments, like Amazon, Microsoft, Apple and The Home Depot. They’re often referred to as blue-chip companies, a term borrowed from the game of poker, where the blue chip carries the highest value.
ETFs are passive funds, meaning no one is managing your investments for you. You won’t pay fees for someone to look out for your money, but the trade-off is that you’re on your own. Only after you’ve maxed out your retirement accounts should you even think about investing in low-turnover ETFs inside a taxable investment account.
Mutual Funds
The best way to invest for long-term, consistent growth is to put your money into mutual funds. A mutual fund is created when a group of people pool their money together to buy stocks in different companies.
Mutual funds create built-in diversification for your investment by spreading your money out. Some of the funds will go up and some will go down, but the historical long-term growth rate of the S&P 500—a common benchmark for the overall U.S. stock market—is 10–12%1. That means when you select good growth stock mutual funds, you can reasonably expect the value of your investments to grow over the long term. But remember that past performance doesn’t guarantee future results.
Unlike ETFs, mutual funds are actively managed, meaning that an investment professional is making decisions about how to invest the fund’s money. There are also thousands of different mutual funds to choose from. Work with an investment professional when you’re choosing specific funds. Don’t go it alone.
The four types of mutual funds that we recommend are:
- Growth and income funds: These are the most predictable funds in terms of their market performance.
- Growth funds: These are fairly stable funds in growing companies. Risk and reward are moderate.
- Aggressive growth funds: These are the wild-child funds. You never know what they’re going to do, which makes them high-risk, high-return.
- International funds: These are funds from companies around the world.
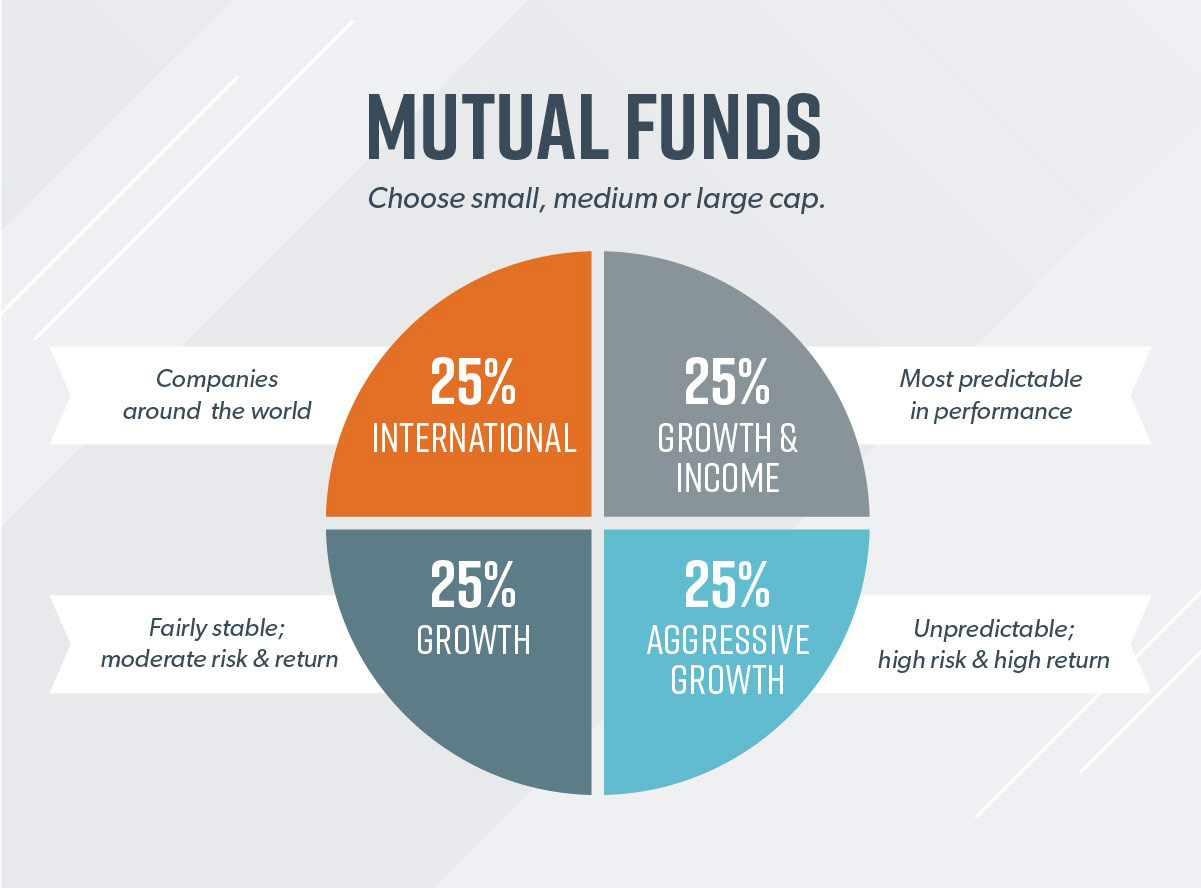
Put 25% of your investment money into each of these four funds. Let’s say the aggressive growth fund has a rough year. The other three are still there to hold the line and keep your overall balance moving in the right direction.
That’s what diversification actually buys: the upside of higher-risk funds without one fund’s bad year taking down your whole plan. You don’t have to avoid risk to invest smart. You just have to spread it out. And that’s the real difference between investing in good growth stock mutual funds and betting it all on a single stock.
For individual investors, common stock held through growth stock mutual funds is the best way to invest in the market.
What Is Stock Market Capitalization?
Capitalization, or cap for short, is the total value of a company’s outstanding shares, and it’s the label you’ll see tacked onto most mutual fund names.
Here’s how companies get sorted:
|
Category |
Value of Company’s Outstanding Shares |
|
Small-cap |
$300 million to $2 billion |
|
Mid-cap |
$2 billion to $10 billion |
|
Large-cap |
Over $10 billion |
Now, let’s put this together with an example. A large-cap, growth stock mutual fund is made up of big companies (worth more than $10 billion) that are growing—think back to companies like Amazon, Meta and Microsoft. A small-cap, aggressive growth fund is made up of small companies, like tech start-ups, that have a higher chance of investment gains but also a higher chance of failure.
How Do Stocks Make Money?
Stocks make money in two ways:
- Price appreciation: This happens when the stock’s price rises over time. When you sell for more than you paid, you pocket the difference. This is the “buy low, sell high” game.
- Dividends: Some companies pay stockholders a regular share of their earnings. Collecting dividends means you’re getting paid just for holding the stock, even if the price doesn’t move.
The best way for you to make money on stocks is by investing in growth stock mutual funds and patiently waiting. If that sounds boring, you’d be right for now. But a long-term approach lets the two most powerful forces in all of finance work together: time and compound interest. Here’s an example:
Let’s say you plan to retire at age 60. The average annual wage in the United States today is around $70,000.2 If you invest 15% of that ($875 a month) consistently into good growth stock mutual funds at an 11% rate of return from age 30 until age 60, you’ll retire with about a $2.45 million nest egg. Over time, you’d put in around $315,000 and gain over $2 million in extra growth. All from simply investing in your workplace 401(k) and/or a Roth IRA and letting time do its thing. Still sound boring?
The market is like a roller coaster. And your job is to ride it out and stay patient. The worst decision you can make on a roller coaster is to jump off in the middle, either through panic or trying to time the market. Ever hear the story about the tortoise and the hare? The same lesson applies to stocks: Slow and steady builds wealth. Fast and reckless builds regret.
Here's a Tip
Stocks build wealth long term, but only when you approach them the right way. That means investing through your retirement accounts, choosing to fill them with diversified growth stock mutual funds, and staying invested for the long haul.
Make an Investment Plan With a Pro
SmartVestor shows you up to five investing professionals in your area for free. No commitments, no hidden fees.
Should I Invest in Stocks?
Yes. Used the right way, stocks are one of the most powerful wealth-building tools available, and getting started is simpler than most people think.
All it takes it your workplace 401(k). Investing there is easy (contributions come straight out of your paycheck), tax-advantaged, and often paired with a company match. That match is free money you don’t want to leave on the table! If you don’t have access to a 401(k) through your job, a Roth IRA gives you that same tax-advantaged growth on your own, plus tax-free withdrawals when you turn 59 1/2 if you’ve held the account for at least five years.3
Hear us on this, investing is important! Stuffing your retirement savings under a mattress or burying it in the backyard like a pirate won’t keep up with inflation.
How Do I Invest in Stocks the Right Way?
Here’s the best way to invest in stocks, step by step:
- Get debt-free and build a fully funded emergency fund that supports 3–6 months of expenses first (Baby Steps 1, 2 and 3). Don’t invest while you’re carrying high-interest debt or living one flat tire or emergency room trip away from a total financial meltdown. This is the foundation everything else stands on.
- Invest 15% of your gross household income toward retirement (Baby Step 4). Choose growth stock mutual funds spread across four types: growth and income, growth, aggressive growth and international.
- Start with your workplace 401(k). Contribute at least enough to get your full employer match. But don’t count your employer’s contributions as part of your 15%. Treat it as a bonus on top of your own investing.
- Open a Roth IRA and max it out. The tax-free growth is a massive long-term advantage.
- If you haven’t hit 15% yet, go back to your 401(k) and increase contributions until you do.
Also, once you reach Baby Step 4, it’s a good idea to work with a financial advisor who knows the ropes and can teach you how to start investing. They’ll help you build and stick to a plan that works for you. And they’ll keep you from jumping off the roller coaster when things get rough. Make sure they’re professionally qualified and have the heart of a teacher to help you take your next step.
Next Steps
- Find out which Baby Step you’re on.
- Start budgeting with our EveryDollar budgeting app so you know exactly how much you can put toward investing (or your current Baby Step) each month.
- Make sure your emergency fund is fully funded (3–6 months of expenses) before you start investing.
- Use our Retirement Calculator to run the numbers and see what investing 15% of your gross household income could grow to and whether you’re on track for the retirement you want.
- If you’re on Baby Step 4, connect with a financial advisor to build a retirement investing plan designed for your specific situation.
This article provides general guidelines about investing topics. Your situation may be unique. To discuss a plan for your situation, connect with a SmartVestor Pro. Ramsey Solutions is a paid, non-client promoter of participating Pros.
-
How do stocks work for beginners?
-
A company issues shares of stock and lists them on an exchange like the NYSE or Nasdaq. You buy shares through your retirement account, like a 401(k). Your share’s value then moves with how the company performs, investor emotions and broader economic conditions. If the company grows, your share is worth more. If it struggles, it’s worth less.
-
How do stocks make you money?
-
Two ways: the stock price rises and you sell for a gain (price appreciation), or the company pays you a share of its earnings (dividends). We recommend building wealth the smart way through investing in growth stock mutual funds held in retirement accounts rather than trying to pick individual winners.
-
Is buying $10 of stock worth it?
-
The dollar amount isn’t really the point. A few dollars in a single stock won’t meaningfully build your wealth. What actually moves the needle is consistently investing 15% of your gross household income in growth stock mutual funds through your 401(k) and Roth IRA—month after month, year after year. That’s how ordinary people build extraordinary wealth.
-
Can I make $1,000 a month with stocks?
-
It’s possible, but that’s not the point. And chasing a specific monthly income from stocks is a great way to lose money. Stocks are for building wealth over time, not creating a monthly paycheck. If you need money now, focus on increasing your income, budgeting, paying off non-mortgage debt and building a 3–6 month emergency fund. Then invest 15% of your household income for retirement and let time do the heavy lifting.
Get Weekly Insights Delivered Straight to Your Inbox
Did you find this article helpful? Share it!

About the author
Ramsey Solutions

Get proven Ramsey answers fast.