
Common Types of Mutual Funds
 By
Key Takeaways
- There are several different types of mutual funds, like stock, bond, index, or even hybrid mutual funds. You can tell them apart based on the kind of investments they hold.
- Ramsey recommends investing equally in four different types of growth stock mutual funds: growth and income (large cap), growth (medium cap), aggressive growth (small cap), and international.
- Growth stock mutual funds are funds that invest in stocks of companies that are expected to grow faster than the market. They’re a great way to build long-term wealth—and a diversified portfolio.
Choosing the right mutual funds is kind of like shopping for the perfect car. It’s not so bad if you know what you’re in the market for—make, model, features, those kinds of things. But imagine having to pick your dream car out of thousands of options with no idea what made any of them different.
Seriously. It’s the stuff a car buyer’s nightmares are made of. Yet that’s exactly how many investors feel when they set out to choose mutual funds.
Quick Answer
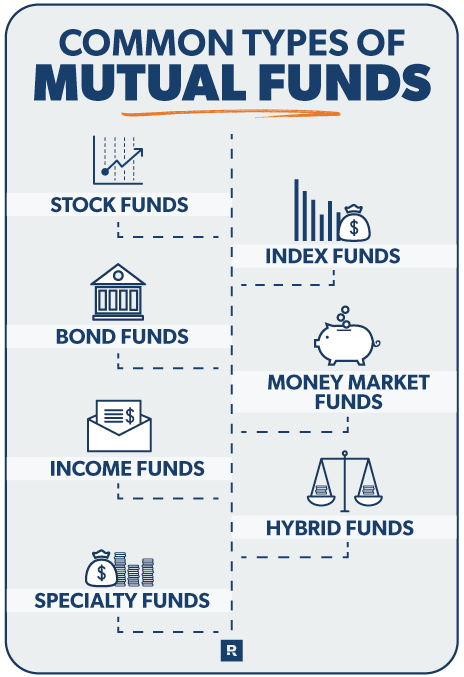
The most common types of mutual funds include stock (aka equity) funds, index funds, bond funds, money market funds, hybrid funds, and specialty funds. You can tell a mutual fund’s category based on what it invests in. For example, stock mutual funds invest primarily in shares of companies, while bond funds invest mostly in loans to governments or corporations.How are you supposed to pick the right funds for your retirement goals if you’re not even sure what you’re looking for? The key to narrowing down your options starts with understanding the main types of mutual funds you can choose from. Let’s break them all down, one by one, so you can make the best choice for your financial future.
What Are Stock Funds?
Stock funds, also known as equity funds, are mutual funds that invest primarily in stocks. Stocks are publicly traded shares of a company. When you invest in a company’s stock, you’re actually buying a small piece of ownership in that company. The only problem is that buying a whole portfolio of different stocks would be incredibly expensive.
That’s where mutual funds come in. Imagine investing in a mutual fund as pooling your money with lots of other investors to buy a large portfolio of stocks that you all share. It’s a great way to achieve diversification without breaking the bank.
Diversification is one of the most foundational principles of investing—and for a good reason. It’s the strategy of reducing risk by spreading out your money over different types of investments.
As the overall value of the stocks in the mutual fund goes up, so does the value of each investor’s piece of ownership. For example, if you put $100 into a mutual fund and the overall value of the stocks inside it rose 10%, your share would now be worth $110.
Of all the types of mutual funds, stock funds are usually the most prone to price swings. But they also carry the greatest potential for growth and a higher rate of return over the long haul. Each mutual fund is run by a team of professional managers who choose which stocks to include in the fund’s portfolio.
Their goal is to pick a collection of stocks that’ll increase in value faster than market indexes like the S&P 500. This index includes the 500 largest U.S. companies that sell shares in the stock market and it is often used to measure the performance of the stock market at large.
But while fund managers try to beat the market, some are better at it than others.
As you learn how to invest in mutual funds, we always recommend focusing specifically on growth stock mutual funds. These are the funds whose managers focus on stocks of companies expected to grow faster than the overall market.
Historically, the average annual rate of return of the S&P 500 is between 10–12%1 over the course of a 30-year period. But if you invest in the right mutual funds, you can collectively beat the stock market over time.
Investing in mutual funds automatically helps diversify your investments. But you know how you can score even better diversification? By investing in more than one type of mutual fund.
That’s why we recommend splitting your investments evenly (25% each) between four different types of mutual funds. Let’s take a closer look at how to identify them.
What Are the Four Categories of Stock Mutual Funds?
Stock mutual funds can be broken down into four different categories: growth and income (large cap), growth (medium cap), aggressive growth (small cap), and international.
Which category a fund falls into depends on the type of stocks it invests in. For example, as you may have guessed from the tell-tale name, international stock mutual funds invest in stocks based outside the United States.
The other three types of stock mutual funds focus on investing in stocks that have something else in common: market capitalization or market cap. Market cap is the total value of a company’s outstanding stock shares—which is a common way to measure the size of company.
Here’s how it breaks down:
- Small Caps: Companies with a market cap of less than $2 billion
- Mid Caps: Companies with a market cap between $2 and $10 billion
- Large Caps: Companies with a market cap of over $10 billion
Let’s take a look at each of the four types of mutual funds and what you can expect from them:
Growth and Income Funds (Large Cap)
Growth and income funds invest in large-cap companies, which tend to offer slower but steadier growth than smaller companies. The “income” part of their name comes from the fact that these companies often pay dividends, which are profit-sharing payments made to investors. These will usually be some of the calmest funds in your portfolio.
Growth Funds (Mid Cap)
These funds invest in medium-cap companies, which can grow faster than large-cap companies, but are also more prone to price swings.
Aggressive Growth Funds (Small Cap)
Aggressive growth funds invest in small-cap companies, which tend to have the most potential for both growth and rapid price swings. These “wild child” funds can make big gains and losses in a short amount of time.
International Funds
International funds are growth stock mutual funds made up of companies from around the world, and their cap size varies depending on the fund. International funds help you further diversify your money by investing based outside of the United States.
Decode Your Retirement Plan Options
Get a free, interactive guide that takes the mystery out of choosing investments for your 401(k), 403(b), or any other employer-sponsored plan.
What Are Index Funds?
Index funds are a type of mutual fund that simply mirror a stock market index or a particular area of the market. Unlike other stock mutual funds that are actively managed (which means professional managers choose what stocks go inside the fund), index funds only invest in stocks, bonds, or other types of investments that are included in a particular index. That’s called passive management—copy, paste, repeat!
A great example of an index fund is the S&P 500. If you invest in an S&P 500 index fund, you’re essentially buying shares of the 500 companies that are listed on that index. You may also see index funds packaged as exchange-traded funds (ETFs).
Some investors claim index funds are more profitable in the long run because you won’t pay management fees. But there are plenty of professionally managed mutual funds that outperform index funds consistently enough to make up for the additional fees.
What Are Bond Funds?
Unlike stock mutual funds, bond funds invest primarily in either government or corporate bonds. Bonds are basically loans that investors make with the expectation of being repaid with interest. While the returns from growth stock mutual funds can be harder to predict, bond funds have a steady rate of return, which is why they’re sometimes called fixed-income funds.
This might seem like a safe and dependable investment, but let’s take a step back and remember that the goal of investing is to build wealth. Long-term government bonds have a history of yielding between 5–6%2 at most. But this just barely outpaces inflation, which averages between 3–4% each year.3 Even though bonds feel less risky than stock funds, you run the risk of not building enough wealth if you don’t grow your money!
What Are Money Market Funds?
Money market mutual funds are similar to bond funds because they also loan money to governments, banks, and other companies in exchange for interest. The difference is that while bond funds tend to make loans for longer periods of time, money market funds loan money that’s supposed to be paid back to investors in less than a year.
Most of the time, these are even worse than bond funds for building wealth! As of 2026, the average money market fund yields less than a 4% average rate of return.4 That means that if inflation rises over 4%, your investment might even lose value.
Think of a money market mutual fund as a babysitter for your money. It watches over it and keeps it safe, but it’s so afraid of risk that it doesn’t leave much room for growth.
When choosing mutual funds, it’s best to steer clear of money market funds. Much like bonds, they’re more of a forced savings plan than a solid investment tool. Here’s the deal: You can’t afford not to take some risk when it comes to growing your money.
How Do Mutual Fund Types Compare?
Now that you’re familiar with stock, bond, and money market funds, let’s compare them all side by side to see how they stack up.
|
Fund Type |
Risk Level |
Potential Return |
Ramsey Recommendation |
|
Stock Funds |
Highest |
10–12% historically1 |
Make these the foundation of your retirement portfolio. |
|
Bond Funds |
Low |
5–6% (barely beats inflation)2 |
Avoid: Not a solid enough return for retirement growth. |
|
Money Market Funds |
Lowest |
>4%4 |
Avoid: They barely outpace inflation. |
What Are Hybrid and Target-Date Funds?
Hybrid mutual funds automatically diversify your investments by spreading out your investing dollars between stocks (equity) and bonds (debt). There are two main types of hybrid funds to choose from: balanced funds and target-date funds.
Balanced Funds
With balanced funds, the ratio between stocks and bonds is set and doesn’t change. For example, you’ll commonly see the fixed ratio of 60% equity (stocks) and 40% debt (bonds). If you invested $1,000 in a balanced fund with that ratio, $600 would be used to buy stocks and the other $400 to buy bonds inside that fund.
The goal of a balanced fund is to help investors enjoy some of the growth that comes with investing in stocks while creating a steady income stream with bonds.
The problem with balanced funds is that their performance is usually weighed down by the lower-performing bonds inside the portfolio, robbing you of the potential long-term returns you could have enjoyed if you’d stuck to stock mutual fund investing.
Target-Date Funds
Target-date funds are one of the most common types of balanced funds. They’re based on the asset allocation approach to retirement planning.
Here’s how it works: You assume (and you know what happens when we assume . . . ) that you’ll retire at a certain age, say 65. The fund invests aggressively in growth stock mutual funds when you’re young, but as you age, the fund automatically shifts your investments to money markets and bonds in order to decrease volatility and risk.
If you’re not careful, your target-date fund might be so conservative that inflation starts to kick your butt as you age. We recommend keeping growth stock mutual funds in your portfolio even after you retire. Your money can still grow!
Here's a Tip
Not sure which type of fund you’re looking at? If there are no clues in the fund’s name, check its fact sheet. Sections like the “fund category” or “fund objective” will usually tell you what type of investments the fund focuses on.
What Are Specialty Mutual Funds?
Specialty funds are mutual funds that didn’t get the memo about the importance of diversification. Instead, they focus on choosing investments that revolve around a particular theme. Let’s take a look at several common subcategories of specialty funds.
Sector Funds
Sector funds invest primarily in stocks within a particular sector of the economy. If you wanted to pour your money into technology, for example, you might invest in a sector fund that focuses on buying stocks from companies like Apple, Google and similar tech companies.
Socially Responsible Funds
Socially responsible funds are created to reflect the ethical or moral views of the investors who are interested in “impact investing.” Some of these funds invest exclusively in companies dedicated to a certain cause or set of values. Others focus on companies that meet certain environmental, social and governance (ESG) criteria—such as gender equality or carbon emission reduction.
Funds may also qualify in this category based on what they don’t invest in. For example, they might specifically refuse to buy stocks in companies that produce products like tobacco. Just be sure to do your research—some of these funds perform better than others, but plenty offer much lower returns than traditional mutual funds. If your faith guides your investing, you may also want to look into Christian mutual funds.
Commodity Funds
Commodity funds invest in precious metals like gold and silver, raw materials and natural resources like oil and natural gas, and agricultural goods like corn and wheat. But despite everything those late-night infomercials might try to tell you, there are major problems with commodities. They’re always going up and down, with prices based more on fear and greed than anything else, and they bring in poor returns over time. Don’t get caught up in the commodities craze!
What’s the Best Way to Invest in Mutual Funds?
The best way to invest in mutual funds is to build a diversified portfolio through a tax-advantaged retirement account. But remember, we only recommend investing after you’re completely out of debt and have a fully funded emergency fund with 3–6 months’ worth of living expenses.
At that point, invest 15% of your annual income and spread it out evenly over the four different types of mutual funds: growth and income, growth, aggressive growth, and international.
Mutual funds are a great investing tool. If you choose the right ones, you’ll be able to build wealth, retire with dignity, and be a blessing—not a burden—to your loved ones and community by having plenty to share.
You can buy growth stock mutual funds from any broker, but you can also invest in them through your retirement plan at work. Retirement savings accounts, like 401(k)s, also come with nice perks like a tax advantage and an employer match—code for free money!
That said, 401(k) plans aren’t without limits. Employer-sponsored retirement plans usually only have a handful of mutual fund options to choose from. So once you’ve invested up to the match—or if you don’t have access to a 401(k)—it’s worth looking into the benefits of a Roth IRA with help from an investment professional. For a deeper walkthrough of the process, see our article how to invest in mutual funds.
A Roth IRA gives you two awesome benefits. First, you have the freedom to buy any mutual fund you want to add to your portfolio—and there are thousands of funds out there to choose from. And second, you get some sweet tax advantages—like tax-free growth and tax-free withdrawals in retirement—which help your investing dollars stretch even further. It’s a no-brainer!
Work With an Investment Pro
Working with an investment professional can go a long way toward taking the guesswork out of investing for retirement. Whether you have questions about what type of mutual funds to choose or anything else along your retirement journey, you’ll always have someone to help you make informed financial decisions.
Next Steps
- Use our Investment Calculator to see whether you’re saving enough for retirement and how investing just a little more each month can make a huge difference.
- Get an in-depth look at everything you need to know about investing—from the basics of mutual funds to powerful tax-saving strategies—in our free Ramsey’s Complete Guide to Investing.
- Find an investment professional who leads with the heart of a teacher. The SmartVestor program can help you find a pro who values serving over selling.
This article provides general guidelines about investing topics. Your situation may be unique. To discuss a plan for your situation, connect with a SmartVestor Pro. Ramsey Solutions is a paid, non-client promoter of participating Pros.
Get Weekly Insights Delivered Straight to Your Inbox
Did you find this article helpful? Share it!

About the author
Ramsey Solutions

Get proven Ramsey answers fast.